28 Jan 2022

Save family money by taking a monthly allowance for yourself!

Whenever I speak with someone in my family who’s running a business, I tell them to always draw a salary for themselves. I tell them, “Take some money out for yourself every month. If you can’t afford to take ₹10,000 a month, take ₹2,000 a month. But your personal expenses should all come from your own salary. Spending for business needs and personal needs from the same bank account will either lead to excessive spending, and/or confusion about your cash flow.”

As new business owners, they are reluctant to draw a salary for themselves: they feel they should work without a salary until the business is profitable. Taking money out for their personal needs looks selfish to them. But the reality is that they have their own personal expenses, and they often end up spending business capital without realising it.

Picture showing a wallet with money
Image credit: mohamed hassan form PxHere

We always have clarity of thought when we advise others. We conveniently forget or ignore that advice in our own matters. That’s exactly what I was doing too: I was spending family money for my own personal expenses!

I manage money in our household. I take care of cash flow management, saving for recurring expenses (such as insurance premiums, school fees, etc), investing for future needs, and so on. In addition to our main investment portfolio, I also have a “fun portfolio”. The main portfolio is for the family’s needs, so it’s conservative and big in size. The fun portfolio is tiny and has all sorts of random assets that catch my fancy.

Earlier today I was thinking that I should be setting a limit for this fun portfolio. When I was wondering what the limit should be, I realised for the first time that I had been spending family money for my personal expenses (i.e. building this fun portfolio). Oops! I immediately added a certain sum as my allowance to our monthly budget. Whatever personal expense that I have, it must come from that allowance.

Having this arrangement is so liberating. Now I can buy random flashy assets without feeling guilty about splurging family money on random things! It’ll also force me to trim the portfolio by selling some old assets when I want to buy a new asset but I don’t have enough money.

It’s counter-intuitive how taking some money out for my personal expenses ends up saving family money in the long run.
27 Jan 2022

My money management goal for 2022

Ever since I started tracking my expenses in 2019, one thing has been bothering me: I spend more than I earn through regular salary. I am not going broke, though. I have other irregular income too. My total income (salary + irregular) is more than my expenses, so I have some money left over for saving/investing.

This is likely irrational, but I want to spend less than my salary income. Every month I notice that the expenses are more than the salary income, and that stresses me out. As we all know, such a consistent stress is bad for the mind and also bad for the body. And I do notice the impact of this stress.

I don’t know what the solution is. Maybe I can recalibrate the expectations to live within the total income (instead of within the salary income). Maybe I need to come up with a novel way of accounting so that the spending looks healthy. (Reducing expenses is not really an option because I don’t want to downgrade the quality of life.)

I think this is a good money management goal for 2022. What good is money and wealth if you can’t be happy!

25 Dec 2021

How to think about emergency fund

Every sane person I know agrees on this: you should not look for returns from your emergency corpus. “Keep the money in highly liquid forms, such as bank deposits or liquid debt funds; never buy volatile assets with that money,” they advise. I did not understand this advice. “What’s the harm in investing, say 10 to 25% of the corpus in equities?” I thought. The other 75 to 90% is not volatile, so you have access to cash when needed. The exposure to equities will keep your emergency corpus growing at a rapid rate (over a long duration such as 10 years).

This line of thinking led me to put most of my emergency corpus in a hybrid mutual fund. My new financial advisor said that this was a bad idea and asked me to move that money over to liquid funds and bank deposits. “Don’t look for returns from this money,” he said.

Since then, I have been thinking about this. It’s hard for me to do something because “the advisor says so.” I needed a convincing reason for why volatility is a strict no-no. After some thinking, I have come up with an analogy for explaining this.

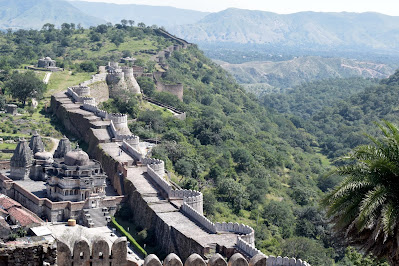
If your wealth is kept inside a fort, the emergency fund is the wall of that fort and the moat around the wall. Anyone who has been to a fort will know: the walls of a fort are so wide that you can drive cars on them.

External wall of a fortress. Image credit: Dr D S Sinha, licensed under CC0

Imagine you are a king. Your fort also has such strong walls as protection. Maybe you have a moat around the walls too. These walls take up so much space! In all likelihood they also cost significant amount of money to keep in good repair. Now you think about it and say, “The walls and the moat take up a lot of space. What a waste of useful land! Wouldn’t it be better if we used this space for farming or housing?” How would your ministers and advisors respond?

This is exactly the reason for keeping the emergency fund liquid and without volatility. When there is an unforeseen need, you’d burn through your emergency corpus before you start to liquidate your long term assets. The wider the moat and the walls are, the safer your long term assets are. The wider the moat and walls are, the more farming land you give up for the sake of protection.

With this picture in mind, I don’t feel too bad keeping all of my emergency corpus in low-yield nonvolatile assets.

28 Nov 2021

Discipline determines the size of your retirement corpus

I am working with a financial planner, and they did some math to make sense of my current portfolio’s value. I knew how many rupees my portfolio was worth, but I didn’t know how many of my financial goals this money was good for. The planner’s way of looking at the corpus gave me a fresh look at the portfolio.

Let’s say the value of my current corpus is X. In about 21 years, I need a retirement corpus that’s at least as large as 3X. Assuming an average annual return of 10%, my existing corpus will double in about 7 years. If I left this corpus of X untouched for 21 years, I’ll have 8X by the time I retire! Such a corpus will be sufficiently large for the kind of retirement I want to have: the kind where I am free to travel, have sufficient buffer for unexpected emergencies, generously spend on life events of children and grandchildren, etc.

While this corpus grows in the background, I’ll also be making fresh investments in the next 21 years. All the new investments that I’ll be making towards retirement in the next 21 years will only grow to X. It’s almost unbelievable how little my new investments will amount to (X) vs how much the existing corpus will grow to (8X).

My main takeaway from this newly acquired knowledge is not that I’ll have an easy retirement. The main takeaway is that I should be financially disciplined enough that I am able to manage my day-to-day expenses and other financial goals without touching the current retirement corpus. The corpus will  have a chance to multiply manifold only if I leave it alone and let it grow.

The word 'discipline' with a man pointing his finger at it
‘Discipline’ by Nick Youngson • CC BY-SA 3.0 •  Pix4free.org

With this revelation, I am able to appreciate the truth behind the saying ‘a bird in the hand is worth two in the bush’. The corpus I already have is precious, and I must do what it takes to protect it. Staying disciplined for the next 21 years is far more important than asset selection or timing the market or chasing current trends. Even if I invest all the new money in an amazing product that gives higher return, it’s going to be incredibly hard to beat my existing corpus.

I always knew that investment duration was a critical factor. But seeing the math for my own corpus makes it all the more real. Discipline is hard when it’s a vague belief. Discipline becomes easier when you know it’ll enrich your life.

22 Nov 2021

Infographic of debt mutual fund durations

Whenever I want to see durations of debt mutual funds, I have to do a Google search, pick a result, and read through some text before I can understand how the debt fund durations stack up. I thought I’d make an infographic so it’s easy to see where each category falls on the spectrum. (I used Groww as the information source.)

The image is not to scale, though many of the boxes should be of a proportional height. Click on the image to magnify it.

Infographic showing durations of debt mutual funds
Infographic showing durations of debt mutual funds; click to make the image larger

When choosing a debt mutual fund, consider both credit risk and interest rate risk. A few previous posts on debt mutual funds: